

This report is part of our cross-asset “What Matters” publication, a new, differentiated product available via a separate subscription. To access the full analysis, please upgrade below or contact us at info@10xresearch.com with any questions.
The Urea Round Trip: How China’s Quota Pen Quietly Vetoed a Fertilizer Trade
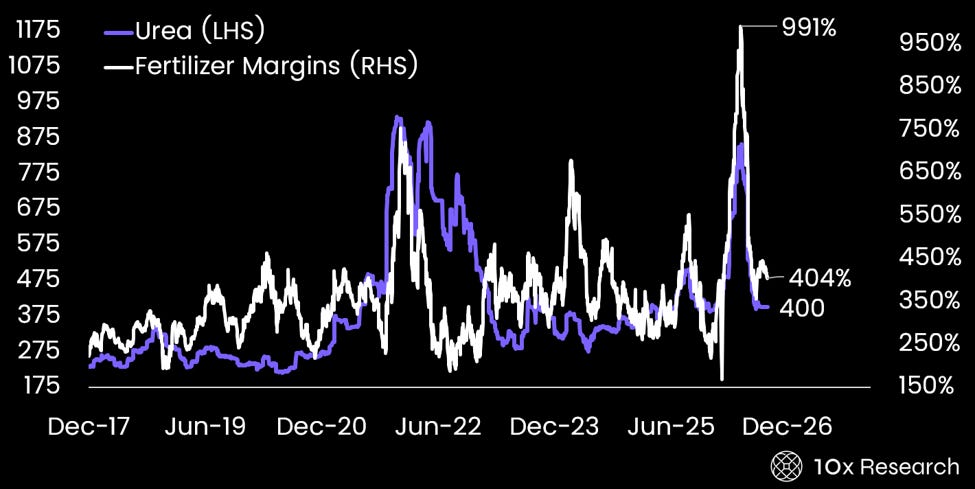
Iran’s war shut the Strait of Hormuz and briefly sent urea prices up 77%, and CF Industries, Nutrien, and the rest of the fertilizer complex looked like a textbook margin trade. Then China opened the export tap, and the whole setup unwound in weeks.
Urea prices (LHS) vs. Fertilizer Margins (RHS) - 991% margins did not last
Why This Report Matters
This report is a live case study in one of 10x What Matters’ core themes: the commodity supercycle and the scarcity of real assets in a world of monetary debasement. Fertilizer sits at the intersection of energy, geopolitics, and food security, three inputs that don’t stay contained to their own markets. When a chokepoint like the Strait of Hormuz gets disrupted, the shock doesn’t just move urea futures; it moves farm costs, grain prices, and ultimately headline inflation, which is the same inflation backdrop that shapes real rates, the dollar, and the relative appeal of hard, apolitical assets like Bitcoin.
But this episode also shows the limits of a purely structural, “scarcity always wins” thesis: a single state actor with enough spare capacity can neutralize a geopolitical supply shock through policy alone, at least temporarily. For subscribers positioning around the broader commodity and sovereignty theme, that’s the more important takeaway than the urea price itself, it’s a reminder to price in the discretionary supply that can show up from non-market actors before treating any chokepoint-driven spike as a clean, durable trade.
Here’s why the bull case was never wrong, and why we’re closing the position anyway. And why investors should keep this trade on their radar regardless, and which alternative expression of it may still be mispriced, given its performance relative to CF Industries.
We’re also adding two more ways to express a bullish view on rising wheat prices to our radar.