
This report is part of our cross-asset “What Matters” publication, a new, differentiated product available via a separate subscription. To access the full analysis, please upgrade below or contact us at info@10xresearch.com with any questions.
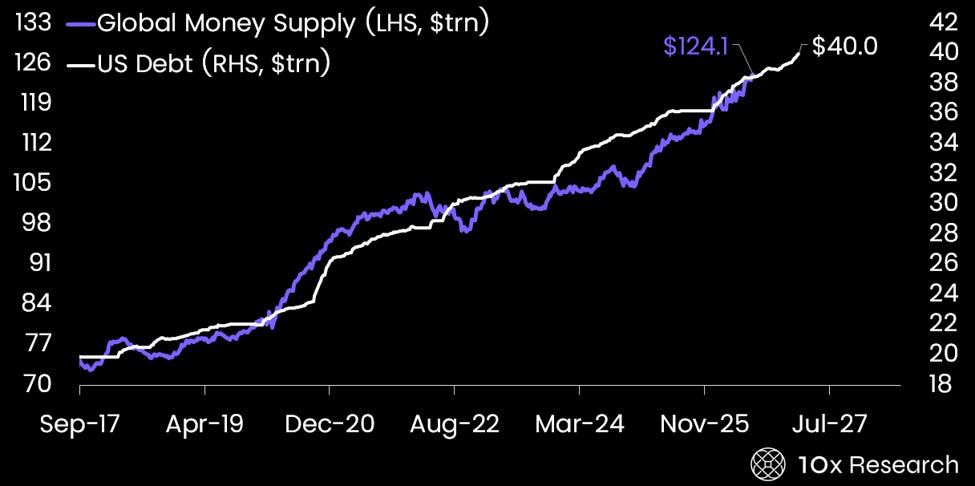
Every major step-change in US debt-to-GDP over the past 50 years has been enabled by one thing, and it just quietly turned back on. At the same time, a demographic shift already locked in decades ago means the workforce funding this debt load will keep shrinking regardless of what policy does next.
This isn’t a US-specific phenomenon; it’s playing out globally, and asset performance since 2020 already confirms the thesis directly. This report lays out the core investment thesis every investor needs to understand: trends unlikely to reverse anytime soon, with real consequences for portfolio returns and composition. It’s a report worth revisiting regularly- the north star for building a resilient portfolio.
Please find attached our 12-page report with the most important charts.
Global Money Supply (RHS) vs. US Debt (RHS)